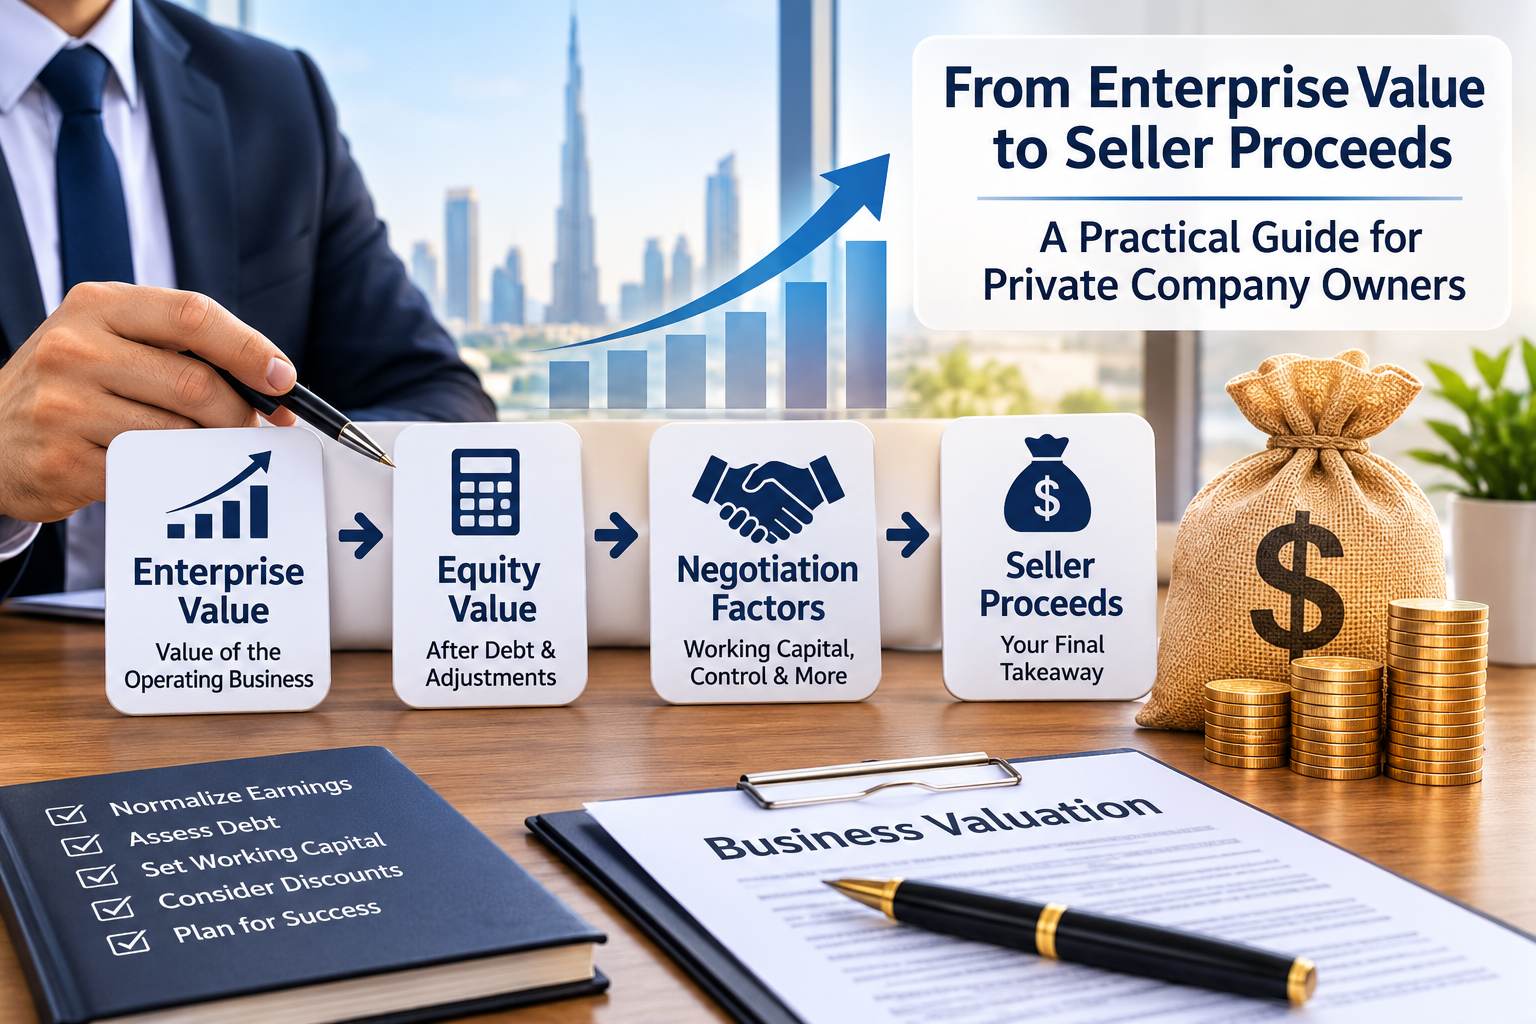
From Enterprise Value to Seller Proceeds: A Practical Guide for Private Company Owners
Owners often hear multiple numbers during a valuation conversation and wonder which one actually turns into a check at closing. The distinction matters. Lenders, buyers, estate planners, and courts may each need a different value, rooted in different assumptions. This article follows one practical path most owners care about: how a valuation of operating performance becomes enterprise value, how enterprise value converts to equity value, and how negotiation points like a working capital peg and minority or control considerations can raise or lower what an owner ultimately receives.
What Enterprise Value Measures in a Private Company Appraisal
Enterprise value represents the value of the operating business before financing choices, often described as a value that excludes cash and debt. Appraisers reach it through methods such as the capitalization of earnings, a discounted cash flow analysis, or market multiples of EBITDA or revenue. A defensible starting point is a formal business appraisal and valuation that defines the standard of value, premise of value, and the approaches most suitable for the company’s economics and data quality.
Critically, enterprise value reflects the assets and liabilities required to run the operations, including a normal level of net working capital. It does not include excess cash, investment portfolios unrelated to the business, or the value of financing choices such as term loans. Think of enterprise value as what a hypothetical buyer would pay for the stream of operating cash flows, independent of how the business is currently financed.
Normalizing Earnings: EBITDA vs. SDE and Adjustments That Hold Up
Appraisals start by normalizing earnings. That means removing unusual events that occurred only once, adjusting owner compensation to market levels, and excluding personal expenses that run through the books. Smaller businesses operating in local markets may be valued on seller’s discretionary earnings because the owner typically handles multiple responsibilities, while larger companies in the lower middle market are usually assessed on EBITDA. The choice affects multiples and comparables. For example, normalizing a founder salary that is below market levels will reduce EBITDA when the adjustment reflects the additional compensation required to hire a manager at market rates.
There is a tradeoff between maximizing adjustments and maintaining credibility. Aggressive adjustments that lack invoices, contracts, or a clear rationale tend to be discounted by buyers or appraisers. Another constraint is the standard of value. Fair market value generally excludes synergies unique to a particular buyer, while investment value may incorporate them. Lease accounting, revenue recognition timing, and accruals such as bonuses and warranty reserves also influence normalized earnings and must be handled consistently with the chosen valuation approach.
From Enterprise Value to Equity Value: Net Debt, Nonoperating Assets, and the Working Capital Peg
To move from enterprise value to equity value, subtract debt and other obligations treated as debt and add assets not required for operations, while accounting for the cash treatment agreed upon in the transaction. Net debt is generally interest-bearing debt minus the cash eligible to offset it under the agreed definition. Items treated like debt can include certain lease liabilities, accrued but unpaid taxes, deferred consideration owed on prior acquisitions, and customer deposits that function like financing. Assets not used in operations may include surplus cash, a portfolio of marketable securities, or a company-owned airplane not needed for operations. Real estate owned by the company may be treated as operating or nonoperating depending on how cash flows were modeled.
Most deals include a working capital peg, which requires delivering a target level of net working capital at closing. Falling short typically reduces equity proceeds dollar for dollar under the purchase agreement. Seasonal businesses or those with long receivable cycles can see meaningful swings here. A common mistake is counting cash twice. If excess cash is included as an asset outside normal operations, it should not also be counted as a reduction to net debt. Another error is missing obligations not shown directly on the balance sheet, such as certain equipment leases that behave like debt in negotiations.
Control, Minority, and Marketability: How the Standard of Value Changes the Number
Values differ depending on whether the interest appraised is controlling or minority. A controlling interest can reset executive pay, distribute cash, sell assets, or change strategy, which can justify a control premium when it is not already reflected in the valuation method. A minority interest without control may warrant a discount for lack of control and a separate discount for lack of marketability due to limited liquidity and transfer restrictions. The chosen discounts depend on the valuation’s purpose and empirical support, not arbitrary percentage ranges.
Purpose also affects the standard of value. Fair market value assumes a hypothetical willing buyer and seller and typically excludes unique synergies. Investment value allows assumptions particular to a buyer and may be higher for a strategic acquirer. Premise matters too. A going concern premise values the business as an operating entity, while an orderly liquidation premise considers outcomes from selling assets individually. These choices shape both the earnings base and the applicable adjustments, and they must be stated clearly in the report.
Two Quick Examples That Clarify Common Misunderstandings
Consider a machining company with steady EBITDA and an enterprise value based on a market multiple. The owner has a sizable line of credit drawn to finance inventory, a term loan on equipment, and cash that fluctuates with seasonality. The appraisal concludes enterprise value using normalized EBITDA that accounts for an owner salary below market levels. When converting to equity, the term loan and drawn line reduce value, certain equipment leases are treated as obligations similar to debt, and only cash beyond the amount needed for operations may qualify as excess under the transaction terms. If receivables are below the working capital target at closing, proceeds drop further despite a healthy enterprise value.
Now consider a software firm with recurring revenue, deferred revenue liabilities, and convertible notes. Normalization shifts focus from SDE to EBITDA as the company develops a more formal management structure. Enterprise value may be modeled with a discounted cash flow that reflects customer turnover, customer acquisition cost, and lifetime value dynamics. To reach equity value, the notes may reduce proceeds depending on their conversion or repayment terms; unearned revenue obligations may be treated as debt, and cash raised but not required for operations may be added back. If the standard of value is fair market value, synergies unique to the buyer’s platform are excluded, keeping the conclusion grounded in what a typical market participant would pay.
Owners who understand this chain of logic are better prepared for due diligence and fewer surprises at the letter of intent stage. Before relying on any single number, ask how earnings were normalized, which standard and premise of value were used, whether the appraisal concluded enterprise or equity value, how net debt and obligations treated like debt were defined, and what working capital target was assumed. These elements connect directly to the proceeds at closing and can be managed ahead of time through cleaner books, support for earnings adjustments, and policies that stabilize working capital. That preparation helps turn valuation theory into a transaction outcome that matches expectations.